Canterbury & Kent
Sub-5% Mortgage Deals Vanish: October 2026 Kent Buyers Face a New Reality
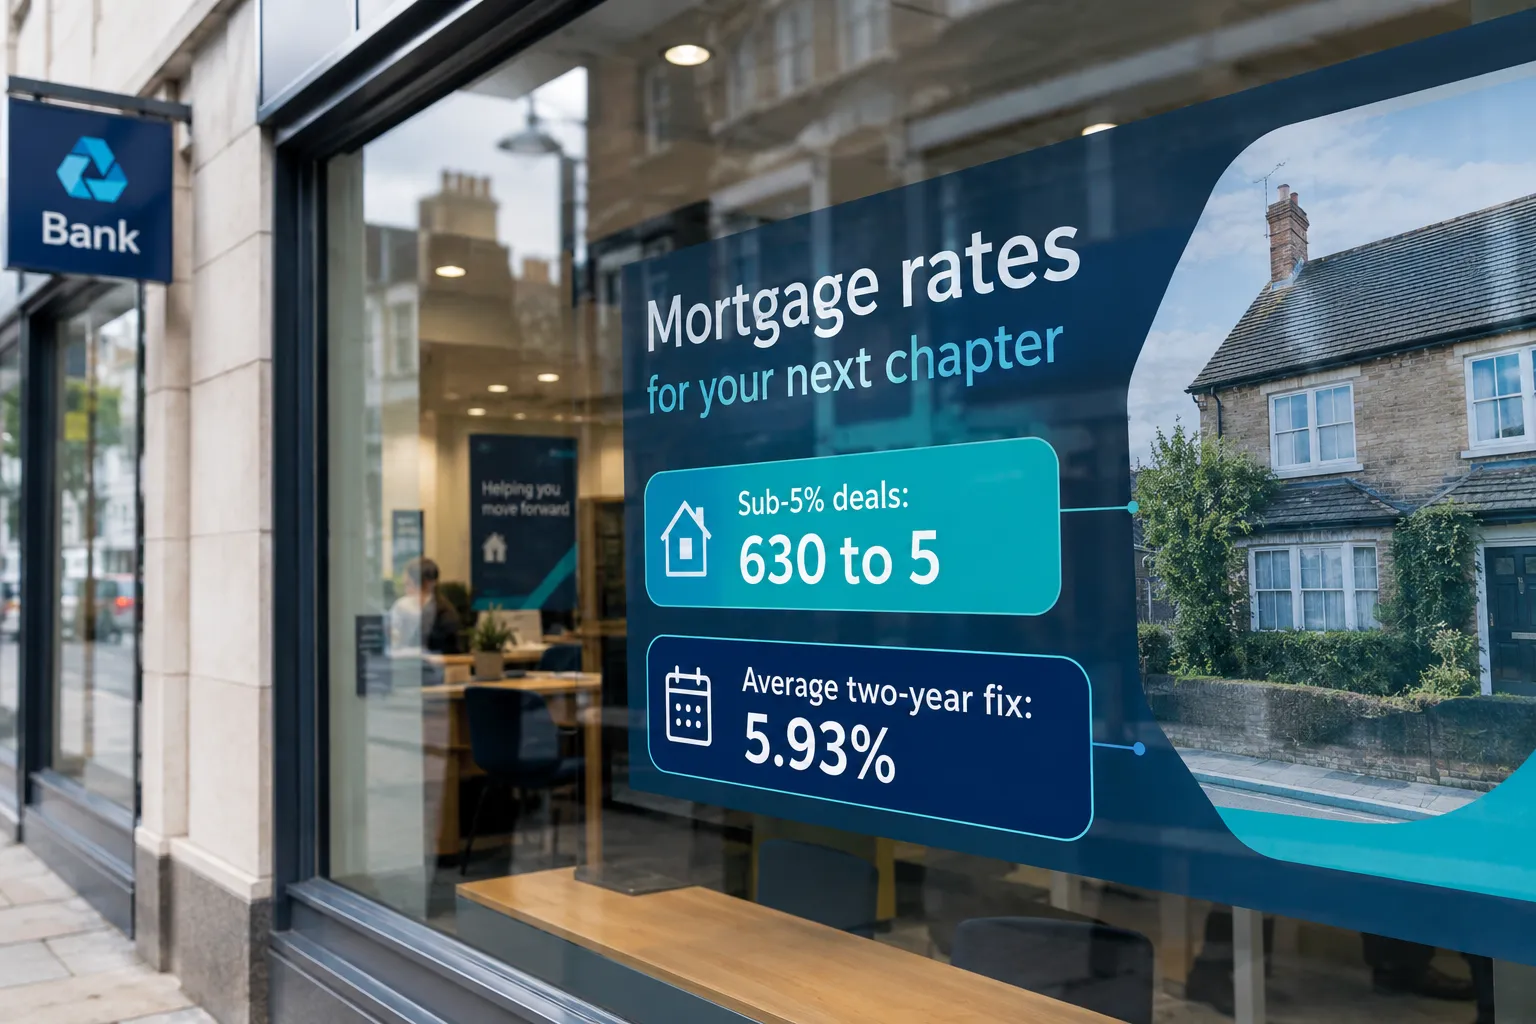
Five. That is how many two-year fixed mortgage deals priced below 5% remained on the UK market as of 1 October 2026, down from roughly 630 just four weeks earlier. For anyone house-hunting or remortgaging in Canterbury, Faversham, Ashford or anywhere else in Kent, that single statistic tells the whole story of a mortgage market that has shifted beneath borrowers’ feet almost overnight. Sub-5% mortgage deals vanish October 2026 Kent buyers now face a genuinely different arithmetic than they did at the start of September, and the change has arrived faster than most brokers expected.
This news briefing from Canterbury Surveyors explains exactly what happened, why it happened, and what Kent buyers, sellers and remortgagers should do next.
Key Takeaways
- Moneyfacts data confirms sub-5% two-year fixed deals fell from around 630 to just 5 between early September and 1 October 2026; five-year sub-5% deals fell from 638 to 7.
- Average two-year fixed rates now sit at 5.93%, the highest since July 2024; average five-year fixes are at 5.94%, the highest since October 2023.
- On a typical £250,000 mortgage, repricing adds roughly £52 a month on a two-year fix and £47 a month on a five-year fix versus a month ago.
- The Bank of England held Bank Rate at 3.75% on 17 September 2026, but markets price a 92% chance of a rise to 4% on 5 November 2026, with more increases likely over the next 15 months.
- Nationwide’s House Price Index shows annual UK growth slowing to 0.8%, with southern England prices down 0.1% annually, meaning Kent sellers should temper price expectations.
What Happened This Week: Sub-5% Mortgage Deals Vanish for October 2026 Kent Buyers
The scale of the repricing has caught even experienced mortgage brokers off guard. Moneyfacts data reported on 1 October 2026 shows the number of two-year fixed deals priced below 5% collapsed from around 630 in early September to just 5 by the start of October. Five-year fixed deals below 5% fell almost as sharply, from 638 to 7. The average two-year fixed rate is now 5.93%, its highest level since July 2024, while the average five-year fix stands at 5.94%, the highest since October 2023.
For a household borrowing £250,000 over 25 years, that repricing adds approximately £52 a month on a two-year fix and £47 a month on a five-year fix compared with rates available just a month earlier. Over a two-year fixed term, that is more than £1,200 in extra repayments that simply did not exist in most buyers’ budgets at the start of September.
Lenders moved fast and in step. Barclays raised rates twice during September and pulled its 4.75% two-year and 4.93% five-year deals entirely for new customers. Nationwide lifted fixed rates by 0.3 percentage points across its range. HSBC, TSB and Virgin Money all followed with their own increases. Nick Mendes of John Charcol summed up the mood among brokers, noting that the cheapest sub-5% deals “would be among the first to go” once lenders began repricing, and that is precisely what has happened.
Caitlyn Eastell of Moneyfacts put it bluntly: “the scale of repricing in recent months has been a constant strain for borrowers.” For Kent buyers who had been comparing quotes since the summer, deals that looked attractive in August may no longer exist today.
Why Mortgage Rates Are Rising Across the UK and in Kent
The root cause sits with the Bank of England and the inflation outlook. The Bank held Bank Rate at 3.75% on 17 September 2026, but the vote was close: six members backed holding, while three wanted an immediate rise to 4%. That split signals real appetite within the Monetary Policy Committee for tighter policy, and markets have taken notice.
The next decision lands on 5 November 2026, and markets are currently pricing roughly a 92% chance that Bank Rate rises to 4%. Beyond that single move, traders expect more than a full percentage point of increases over the following 15 months. Governor Andrew Bailey has already signalled this direction, stating that Bank Rate “may need to increase.”
Inflation is the driver. CPI inflation hit 3.1% in August 2026, up from 2.9% the month before, and the Bank has warned it could climb above 4% in early 2027. Middle East tensions pushing up energy prices are cited as a key contributing factor. Lenders, pricing mortgages against expectations of future base rate moves rather than today’s level, have simply got ahead of the curve, withdrawing cheap deals before the Bank even meets again.
What It Means for Kent Buyers’ Budgets and for Sellers
For buyers in Canterbury and across Kent, the immediate consequence is a tighter budget. An extra £47 to £52 a month on a £250,000 mortgage may not sound dramatic in isolation, but stacked against stamp duty, moving costs and survey fees, it meaningfully narrows what many households can realistically afford. First-time buyers who had been approved in principle at lower rates in August may now find their borrowing power reduced when lenders reassess affordability.
For anyone nearing the end of an existing fixed deal, the clock is ticking. Chris Sykes of MSP Financial Solutions advises borrowers to secure a new rate up to six months before their current fix ends, locking in terms even if the completion date is still some way off. Given how quickly sub-5% deals disappeared this autumn, that lead time has never mattered more.
Sellers should also recalibrate expectations. Nationwide’s House Price Index, published 1 October 2026, puts the average UK property price at £274,251, with annual growth slowing sharply to 0.8% from 1.6%, and a monthly fall of 0.2%. Nationwide’s Robert Gardner noted that earnings are now rising faster than house prices, a dynamic that should gradually improve affordability but which currently caps how much sellers can push asking prices. Southern England, which includes Kent, recorded annual price growth of minus 0.1%, underlining that buyer demand has cooled alongside borrowing costs. Those tracking how the regional picture has evolved through the year may find useful context in our earlier review of Kent’s property market conditions and why independent valuation advice matters.
Practical Steps for Kent Buyers, Sellers and Remortgagers
With rates rising and budgets tightening, a few practical actions can protect Kent households from the worst of the squeeze.
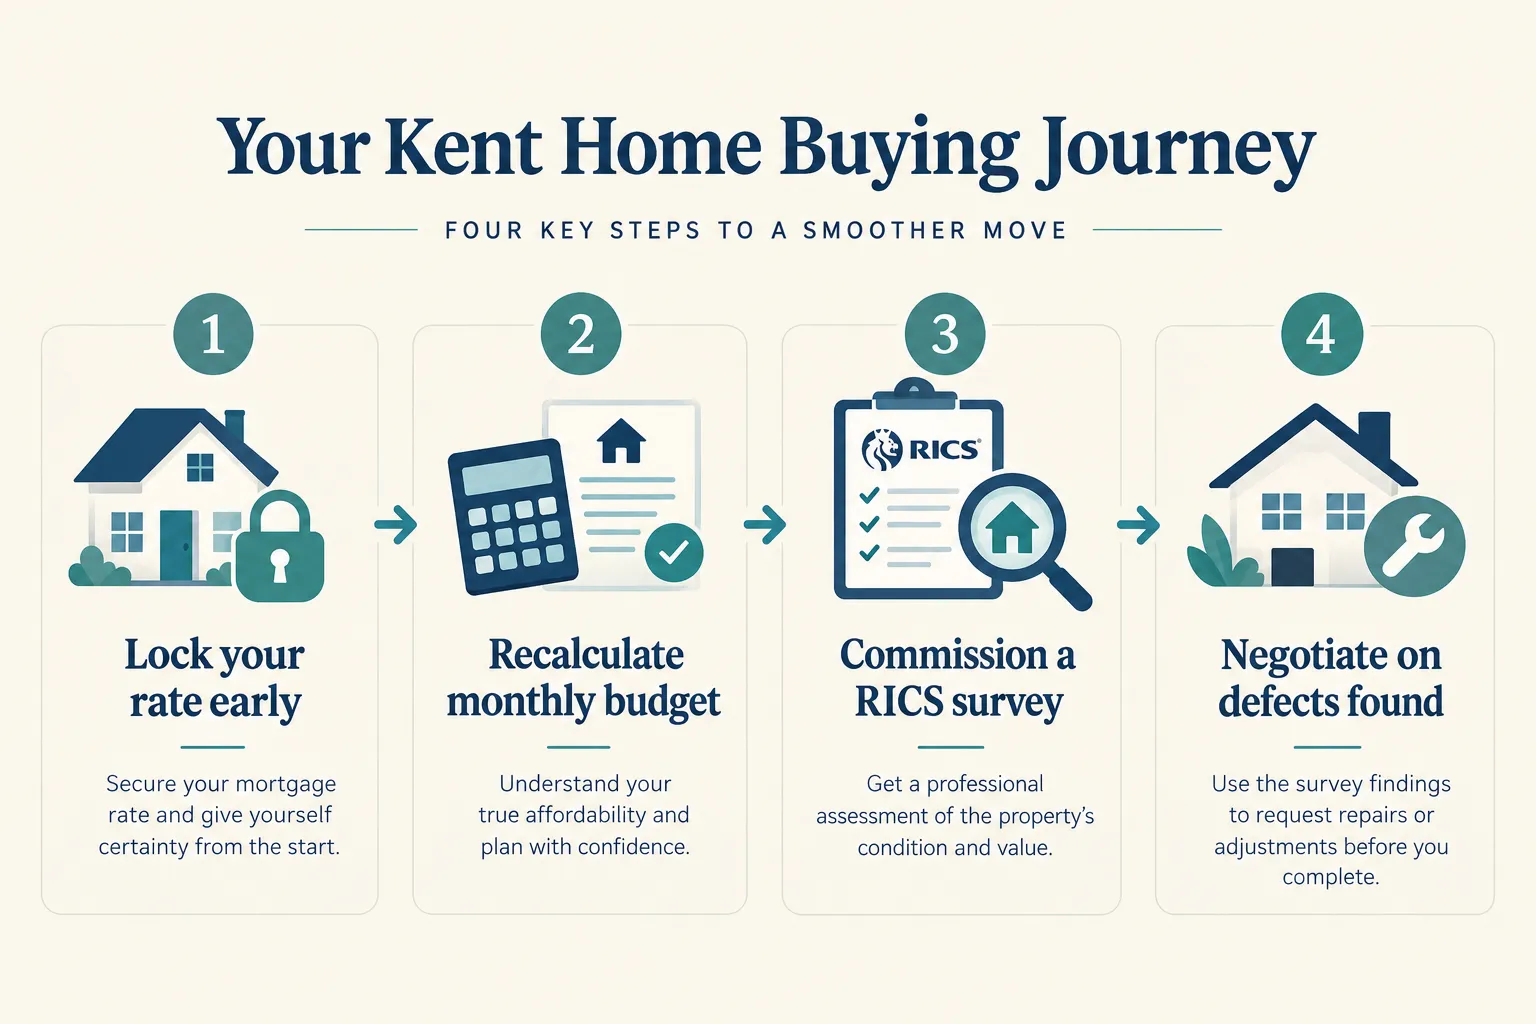
Lock in a rate as early as possible. Many lenders allow borrowers to secure a mortgage offer months ahead of completion, with the option to switch to a lower rate if one becomes available before the deal expires. Given the pace of September’s withdrawals, waiting is now a genuine financial risk.
Rebuild the monthly budget around higher repayments. Factor in the roughly £47 to £52 monthly increase per £250,000 borrowed, and stress-test affordability against the possibility that Bank Rate rises again on 5 November 2026 or beyond.
Commission an independent RICS survey before exchanging. When every pound of monthly budget counts, a RICS Level 2 Homebuyer Report or Level 3 Building Survey can uncover defects that justify a price reduction, effectively offsetting higher borrowing costs. Our guidance on choosing the right valuation-focused report for today’s buyers and on when buyers should insist on a full building survey rather than a basic report explains the difference in detail.
Get a valuation reality-check. With national price growth slowing and southern England in slight decline, an independent survey helps confirm whether an asking price reflects current market conditions. Our review of how defect findings help buyers negotiate against competing offers outlines practical negotiation tactics worth considering before completion.
As a local, RICS-regulated firm, Canterbury Surveyors works with buyers, sellers and remortgagers across Kent to deliver independent survey evidence at exactly this kind of turning point in the market, when every negotiating lever matters.
Frequently Asked Questions
Why did sub-5% mortgage deals disappear so quickly in September 2026? Lenders including Barclays, Nationwide, HSBC, TSB and Virgin Money repriced their ranges upward in anticipation of further Bank of England rate rises, withdrawing their cheapest fixed deals almost simultaneously.
Will Bank Rate definitely rise on 5 November 2026? Nothing is certain, but markets currently price roughly a 92% probability of a rise from 3.75% to 4%, following a close 6-3 vote to hold rates in September.
How much more will I pay on a £250,000 mortgage now? Based on Moneyfacts figures, a two-year fix now costs around £52 more per month and a five-year fix around £47 more per month than deals available a month earlier.
Should I lock in a new rate now if my fix ends in six months? Chris Sykes of MSP Financial Solutions suggests securing a new rate up to six months before a current fix ends, given how fast favourable deals can disappear.
Are Kent house prices still rising? Nationwide’s October 2026 data shows UK annual growth slowing to 0.8%, with southern England, including Kent, down 0.1% annually, so price growth has clearly cooled.
Can a survey help offset higher mortgage costs? Yes. A RICS Level 2 or Level 3 survey can identify defects that support a lower negotiated purchase price, helping buyers manage the impact of higher monthly repayments.
Conclusion
The rapid disappearance of sub-5% mortgage deals marks one of the sharpest repricing episodes Kent buyers have faced in recent years, and it arrives alongside a cooling housing market and a Bank of England clearly weighing further rate rises. Sub-5% mortgage deals vanish October 2026 Kent buyers now face higher monthly costs, tighter affordability checks and a narrower window to lock in favourable terms. Those approaching a remortgage or a purchase should act now: secure a rate early, recalculate budgets honestly, and commission an independent RICS survey to ensure the price paid reflects the property’s true condition. Canterbury Surveyors can help Kent buyers, sellers and remortgagers navigate this fast-moving market with clear, independent, RICS-regulated advice.
Related services from Canterbury Surveyors
Get a fixed-fee quote or call 0204 579 8270.